How an industry built to remove gatekeepers handed the keys to the biggest gatekeepers of all
Bitcoin's promise was simple: no gatekeepers, no permission slips, no middlemen. More than a decade later, the most powerful players in crypto are not decentralized networks at all. They are centralized exchanges, and for many long-time believers that is the industry's greatest contradiction.
The big exchanges market themselves as champions of innovation and financial freedom. But follow the incentives and a different picture appears. They did not come to support crypto. They came to make money from it, and too often they made it from the very people crypto was meant to protect.
The narrative factory
Every cycle has its story. ICOs. DeFi. NFTs. The metaverse. GameFi. Memecoins. Then an endless parade of Layer 1 and Layer 2 chains. Each narrative minted thousands of tokens and billions in speculation, and each time the exchanges rushed to list them, promote them and sell them as the next big thing.
Most investors who bought in believed they were funding the future. Instead, a huge share of those projects collapsed, bled out or vanished, and by many accounts the overwhelming majority of retail buyers lost money, with some putting the figure above 90%.
Here is the uncomfortable part: the exchange got paid either way. Whether a token went up 1,000% or fell 99%, the trading fees came in. An exchange earns from activity, not from quality, and that single fact explains almost everything that follows.
Pre-listing: selling the ticket before the show exists
The clearest symptom is pre-listing. Tokens and perpetual futures open for trading before the project has launched, before the code has been tested and before anyone has proven the economics work. Markets appear around promises instead of products.
Does the exchange stop to ask whether the team will rug pull? Does it run a serious compliance review? The pattern says no. The listing is the product, and the due diligence is marketing copy. Hype beats utility, insiders get a ready-made exit, and retail walks in at the top.
Crypto was supposed to be about innovation and decentralization. Too much of it has turned into a casino where narratives trade faster than technology gets built.
The Layer 2 inflation trick
Layer 2 networks arrived promising cheaper, faster transactions, and many have genuinely improved efficiency. But a lot of them paired that promise with proof-of-stake tokenomics that dangled staking rewards in front of new users.
Those rewards are not free money. They are paid by issuing new tokens, which means inflation. The holder sees a juicy yield percentage while the supply they own a slice of keeps expanding. Unless real demand outruns the new issuance, "yield" is dilution wearing a nicer outfit, and the people who understood that early were usually the ones selling to the people who did not.
The inverted standard: hype gets fast-tracked, resilience gets interrogated
Now the part that frustrates veterans most. Projects with years of proven operation, real decentralization and genuine community participation struggle to get listed. Meanwhile a freshly launched, heavily marketed token can appear on a major exchange almost overnight.
A network that has survived multiple market cycles should arguably earn more recognition than a project whose main achievement is raising venture capital. The reality is often the reverse, and it rewards hype over resilience.
The DigiByte test
DigiByte (DGB) is the case study. It has been running since 2014, a record of around 12 years without a major failure. It never launched through an ICO, it was not built on venture capital, and no company sits behind it. It is a community-driven, decentralized UTXO chain, and its native decentralized stablecoin, DigiDollar, extends that foundation into decentralized financial infrastructure with no centralized issuer to trust.
You would expect a record like that to be welcomed. Instead, supporters say exchanges drag their feet and backtrack, demanding extensive documentation, compliance reviews and legal opinions, and seeming to look for reasons not to list. Yet the same platforms found ways to fast-track trend-driven assets that generate more volume. The standards are not consistent. They are selective.
And DigiByte did the homework anyway. It has obtained a legal opinion letter covering both DigiByte and DigiDollar, a good-faith effort to provide the regulatory clarity exchanges say they want. That level of diligence should be rewarded, not ignored. If compliance is the real concern, what is left to object to?
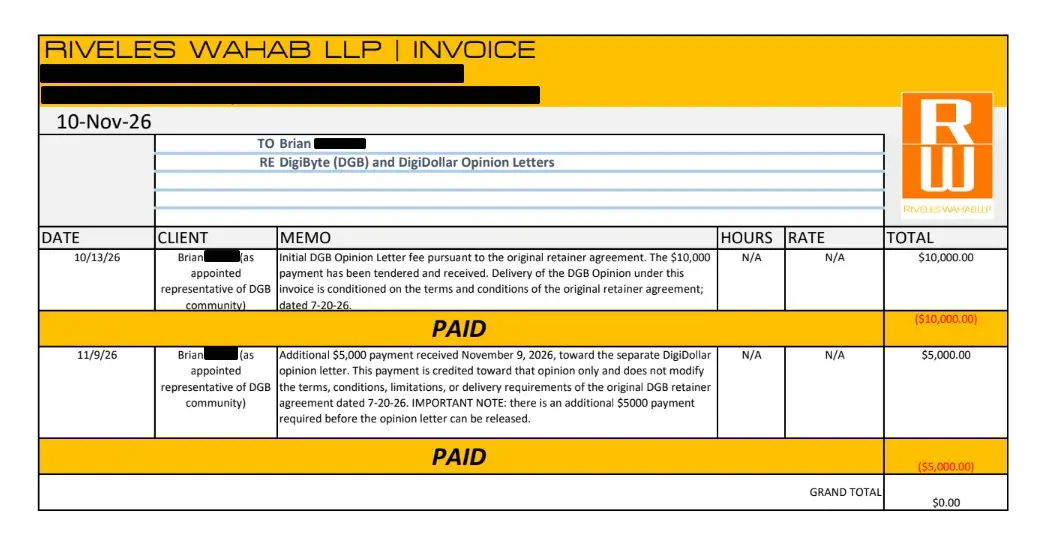
Digibyte & Digidollar Opinion letter
The listing fee problem
There is also the money. Projects have long reported being asked for large payments to secure a listing, along with marketing packages, liquidity programs and promotional campaigns on top.
Which raises the question: if crypto was meant to eliminate gatekeepers, why should a project have to pay an enormous sum to a centralized intermediary just to reach the market? A grassroots network with no treasury and no corporate backer cannot compete with a venture-funded token that can write the check. This looks a lot like the financial system crypto was designed to replace.
The real answer: DEXs and P2P marketplaces
The lesson is not to beg harder for a seat at the centralized table. It is to stop building our future on someone else's permission. A centralized exchange can delist you, freeze you, answer to regulators before it answers to users, and decide which projects deserve exposure. Recent headlines about major exchanges and government pressure show how much power sits in so few hands.
Decentralized exchanges return control to users. You hold your own keys, there is no custodial risk, and no committee decides whether a network is worthy. Peer-to-peer marketplaces go further, letting individuals trade directly with no operator's permission at all. They still face real challenges in liquidity, user experience and accessibility, but they are the closest thing we have to what crypto was meant to be. For projects like DigiByte and DigiDollar, built around decentralization from day one, they are not a fallback. They are home.
Conclusion
Centralized exchanges played a real role in onboarding users and providing liquidity. But their incentives point toward volume and fees, not toward the long-term health of decentralized networks, and they have shown they will take that profit whether the project is a 12-year-old network or a rug pull waiting to happen.
So the question is simple: should crypto's future be controlled by corporations chasing trading volume, or by open networks and peer-to-peer markets designed to cut out the middlemen? The future of crypto will not be secured by gatekeepers. It will be secured by decentralized exchanges and peer-to-peer marketplaces, where the users, not the corporations, hold the power.