Wall Street experienced a transition session yesterday, closing slightly lower following Monday’s rally and held back by US inflation coming in higher than expected. Cryptocurrencies, on the other hand, continued their downtrend, leaving Bitcoin down 4.80% and Ethereum down 8.30% since the beginning of November. Oil remains range-bound, while the October CPI rose +0.4% month-over-month, bringing inflation and the Fed back into focus.
Wall Street remains positive on a weekly basis, while crypto remains weak.
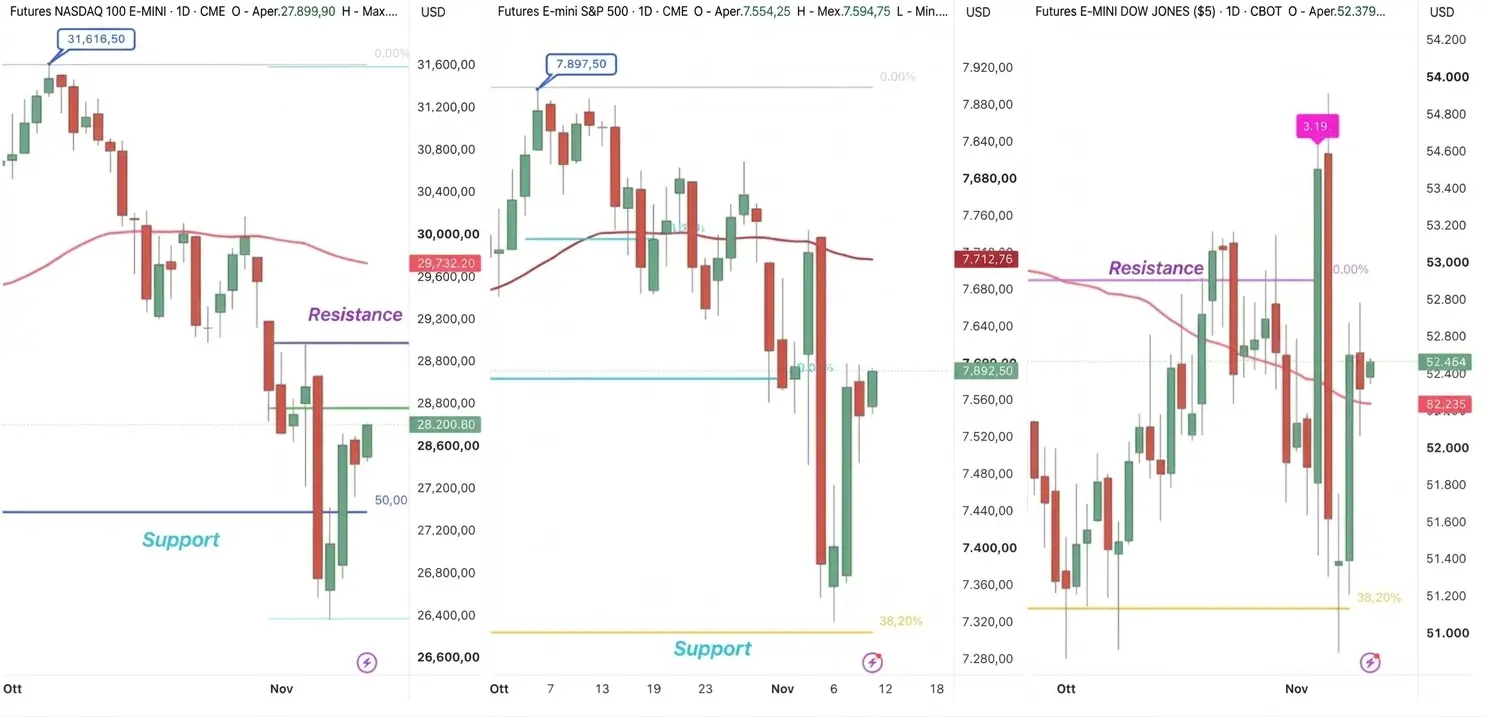
US indices stay positive for the week thanks to Monday's strong rally. Since Monday, Nasdaq futures have gained +4.18%, the S&P 500 +2.59%, and the Dow Jones +2.13%. Yesterday, all three closed with modest losses, restrained by the US inflation figure. Fed Governor Christopher Waller had opened the door to a 50 basis point hike if core inflation came in at least at +0.3%. Core inflation—excluding energy and food—landed right at +0.3%. This morning, ahead of the cash market open, the Nasdaq is trading up +1.37%, the S&P 500 up +0.65%, and the Dow Jones up +0.31%.
CoreWeave raises guidance, Nvidia slows Big Tech
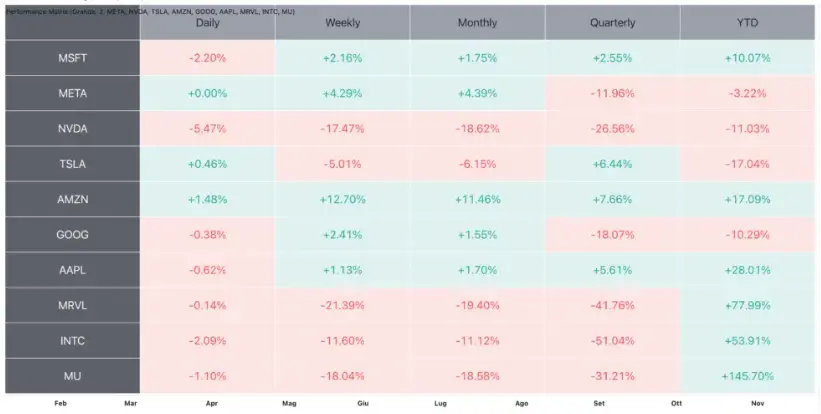
Overnight, CoreWeave, a company that rents out cloud computing power for artificial intelligence, reported its third-quarter results. Revenue rose to $3.66 billion, and full-year 2026 guidance was raised to between $13 billion and $13.3 billion. CoreWeave stock is up +16% in after-hours trading. Among Big Techs, Nvidia weighed the most, falling -5.47% yesterday due to a federal lawsuit involving CEO Jensen Huang. On the performance board, Microsoft fell -2.20%, while Amazon gained +1.48% and Tesla rose +0.46% in yesterday's trading session.
Bitcoin and Ethereum continue downtrend
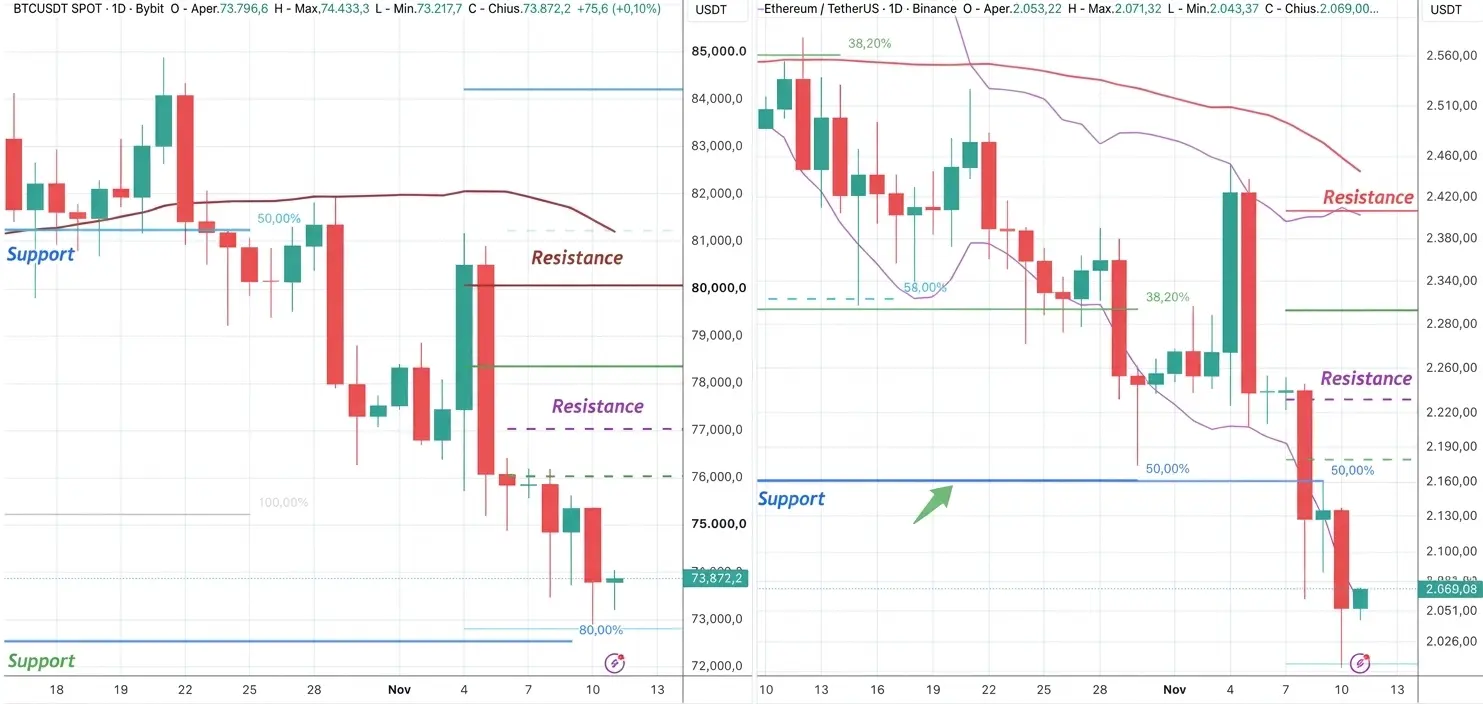
The crypto decline continued yesterday with new period lows, as seen on the daily chart. Today, BTC price (73,746 $ ▼ -1.25%) is currently positive at the time of writing, down -1.40% on a weekly basis and -15.60% year-to-date in 2026. The slide brought the price close to the key support area at 72,000 USDT. Ethereum also remains under pressure, currently trading at 2,064 USDT, now below the primary support level of 2,160 USDT. November's performance stands at a decline of -8.30%, with yesterday's low reaching 2,006 USDT—a level not seen since mid-August.
Fed heading toward a rate hike, Friday brings PPI Today is Veterans Day in the United States, with Wall Street open and the US bond market closed. Following the CPI release, the market now considers a 25 basis point rate hike by the Fed at its December 9 meeting virtually certain. The next key data point is October's Producer Price Index (PPI).
Oil awaits US-Iran deal
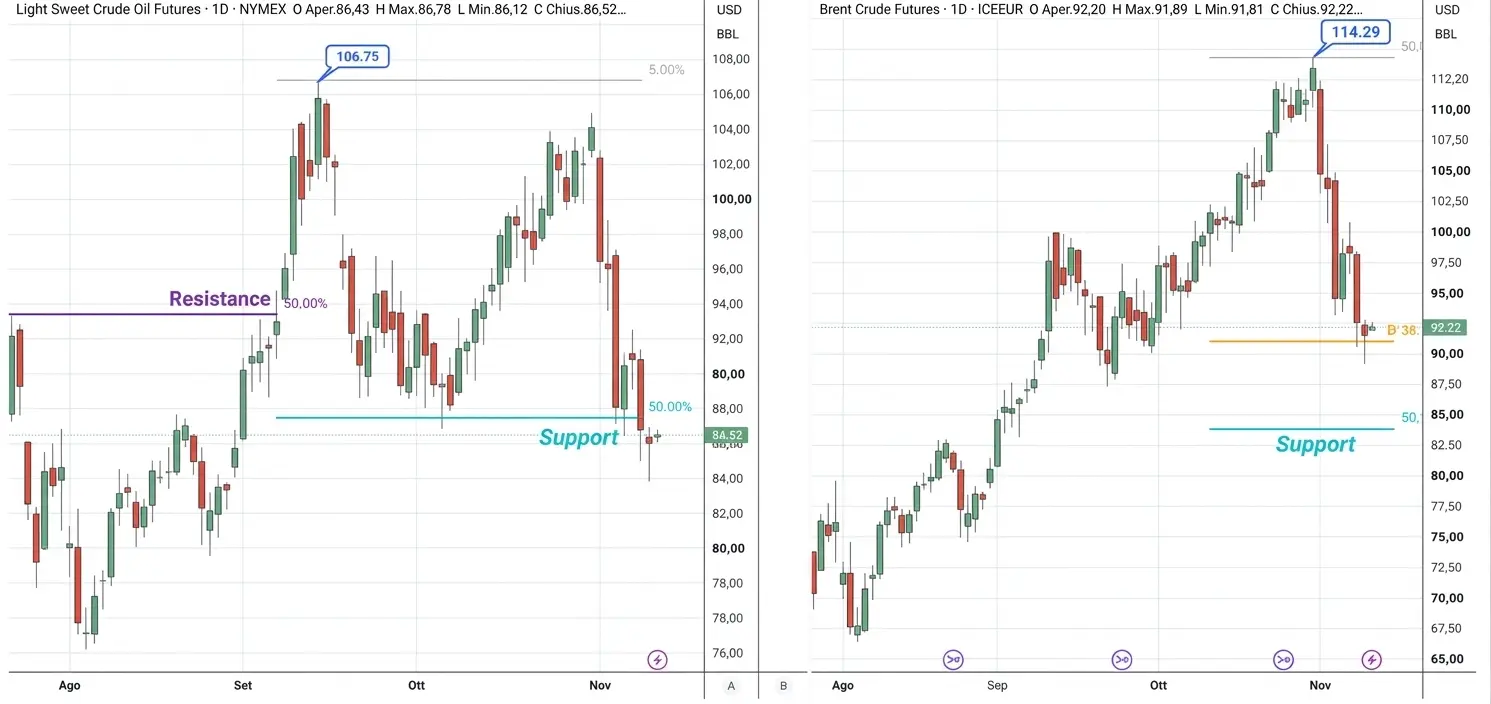
Oil remains in a holding pattern, awaiting an agreement between the United States and Iran regarding the reopening of the Strait of Hormuz. Following a meeting with the Prime Minister of Qatar, Donald Trump called new military action unnecessary while maintaining the naval blockade. Brent is trading at $92.43, up +1.03% in today's session, but down -5.99% on a weekly basis. WTI is trading at $86.43, up +0.45% daily and down -4.84% since Monday, as shown in the chart.