Stablecoins spent much of their first decade mainly as trading collateral. A growing share of activity now looks more like payments and settlement. By 2026, several major jurisdictions had moved from debating stablecoin rules to implementing them: Europe’s MiCA framework was fully in application, its CASP transitional period ended on 1 July 2026, and the United States had enacted the GENIUS Act in July 2025. This article looks at that shift from two vantage points. Cryptopocket, authorised by the Spanish CNMV for the exchange of crypto-assets for funds, describes how a regulated fiat-to-stablecoin corridor works in Europe under MiCA. SimpleSwap contributes general observations about what a maturing market looks like from the infrastructure layer, without reference to any particular regulatory framework.
Block 1. The market grew before the rules arrived
Stablecoin activity has grown large enough that it is now measured against payment networks rather than against other crypto assets. The numbers below come from two separate a16z publications, and they measure different things over different periods, so they are worth reading with their dates attached.
In its State of Crypto report published on 22 October 2025, a16z put trailing-twelve-month stablecoin transfer volume at roughly $46 trillion, and adjusted volume at about $9 trillion once bot activity and other artificially inflationary transfers were filtered out. The same report noted that adjusted activity appeared largely uncorrelated with broader crypto trading volume. That is one data point in support of the view that a meaningful share of stablecoin use sits outside trading, though a single correlation reading is not proof on its own.
A later a16z analysis, published on 24 April 2026, put adjusted volume at roughly $4.5 trillion for the first quarter of 2026. The same analysis reported that velocity, measured as adjusted monthly transfer volume relative to circulating supply, had roughly doubled since early 2024, moving from about 2.6x to about 6x. Supply grew as well over that period, to just over $300 billion by a16z’s October 2025 count, but with velocity doubling, transfer activity has grown faster than issuance. In a16z’s reading, the existing supply is working harder rather than simply getting bigger.
In the same April 2026 analysis, consumer-to-business stablecoin transactions were the fastest-growing category by count, up 128% year-on-year to 284.6 million in 2025 from 124.9 million in 2024.
Concentration remains high. Tether and USDC together accounted for 87% of stablecoin supply in a16z’s October 2025 report, and more than 99% of stablecoins were denominated in US dollars. Any discussion of non-dollar stablecoins therefore starts from a small base, and percentage growth in that segment can look dramatic while the absolute amounts remain modest.
Sources: a16z State of Crypto 2025; a16z, 9 charts on what stablecoins are becoming (24 April 2026)
Block 2. What maturity looks like from the infrastructure layer
There is a pattern that most financial technologies seem to follow. First, the thing works. Then it gets used. Then someone writes down the requirements it needs to meet. Stablecoins look like they are somewhere in that third phase. What is interesting is less that requirements are being written and more that much of the market had already formed the relevant habits before anyone wrote them down.
Maturity in this layer tends to show up as unglamorous requirements. Uptime that can be evidenced. Settlement that behaves the same way on a quiet day and a volatile one. Documentation someone outside the company can read. Failure modes that are described rather than discovered. A support path that exists when a transaction stalls. Little of this was central to the conversation in 2018. Much more of it is expected now, and a good deal of that change came from users and integration partners asking for it rather than from any external requirement.
Fragmentation is part of the same story. The same dollar token can exist across many networks, each with its own fees and finality times, and not all of them are available in every market. For a person who simply wants to move value, that is a choice they did not ask to make. Much of the work in this part of the industry has gone into absorbing that choice so it does not reach the user, and how well a provider does that is one of the things integration partners now compare.
Availability is also becoming a property of a token in a particular market rather than of the token alone. Where a market defines which assets may be offered and by whom, infrastructure has to account for that, and doing so is closer to an engineering problem than a pricing one. This holds in any market that sets such definitions.
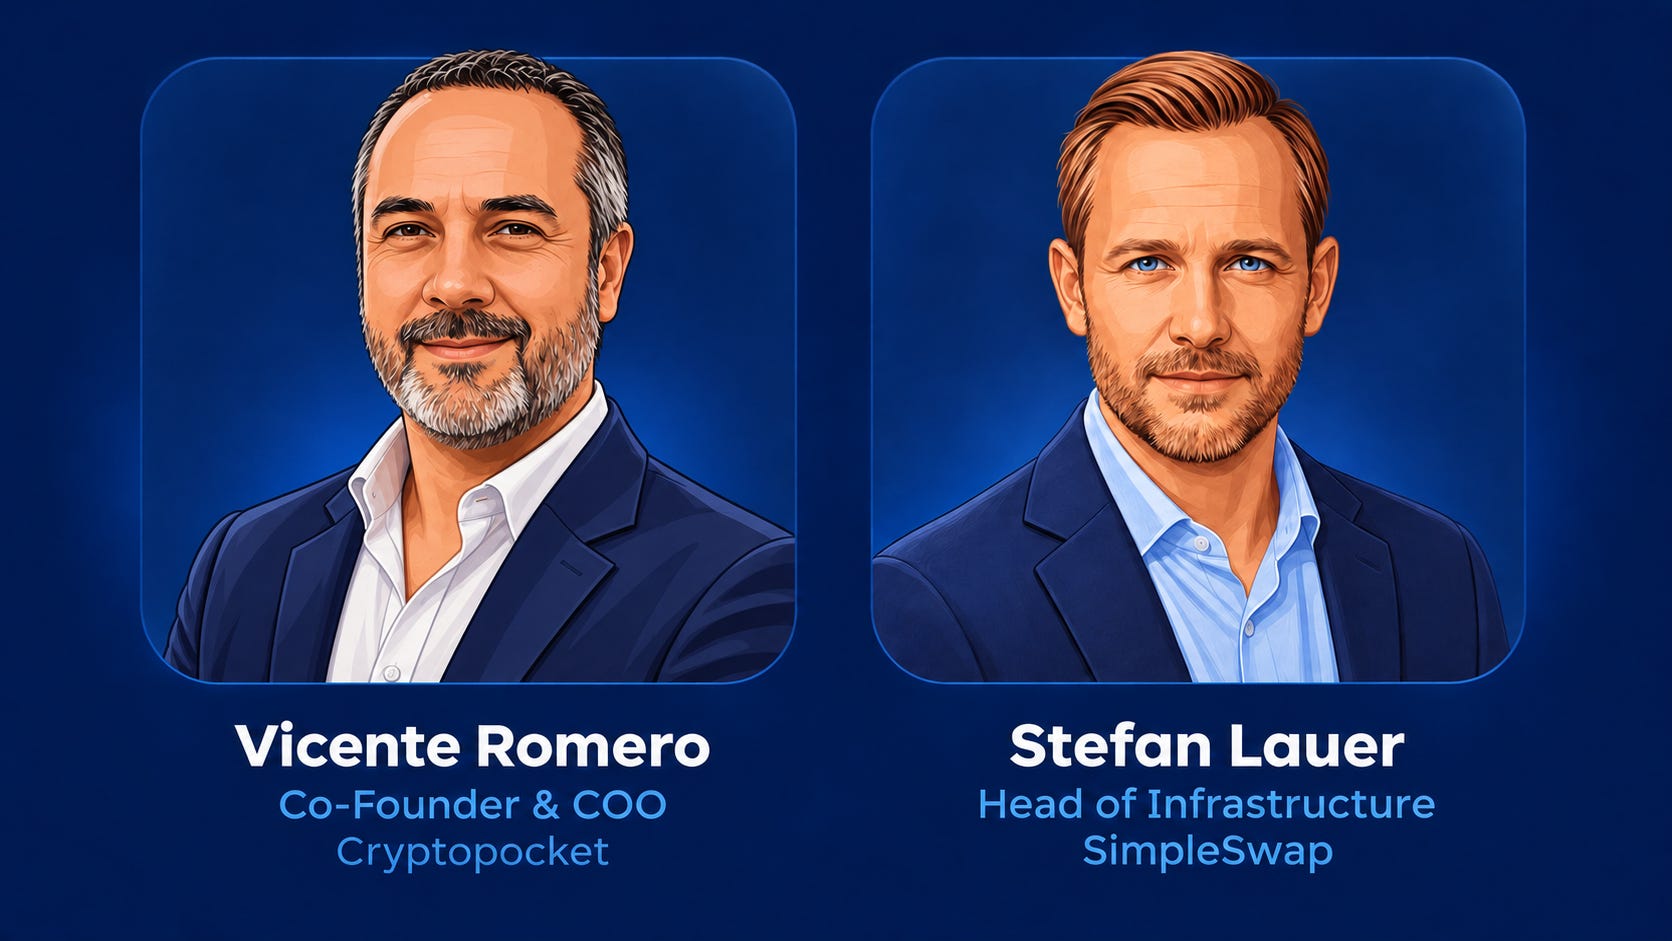
Stefan Lauer, Head of Infrastructure, SimpleSwap: “The first decade of this market was largely about whether something could move at all. The questions that occupy engineers now are narrower and less exciting: does it settle, does it settle the same way tomorrow, and can you explain what happened when it does not. That shift started before anyone was asked to make it.”
Block 3. What MiCA actually changed in Europe
MiCA draws a regulatory distinction between the two stablecoin categories that matter most in Europe. An e-money token (EMT) is a crypto-asset that seeks to maintain a stable value by referencing one official currency. An asset-referenced token (ART) references another value, right or combination of them. For payments and settlement, fiat-pegged stablecoins that reference a single currency therefore sit primarily in the EMT category.
The implementation happened in stages. The MiCA rules for ARTs and EMTs applied from 30 June 2024, while the CASP regime applied from 30 December 2024. In January 2025, ESMA and the European Commission clarified how CASPs should treat non-MiCA-compliant ARTs and EMTs and expected national authorities to ensure compliance as soon as possible and, in any event, by the end of the first quarter of 2025. Pre-existing providers could rely on national transitional regimes only where the relevant Member State allowed them, and only until authorisation or refusal, with an EU-wide final deadline of 1 July 2026. Some Member States used shorter transition periods.
That changes how counterparties should read regulatory status. A pending application is not an authorisation, and after the applicable transitional period an entity cannot continue providing crypto-asset services simply because an application is still under review. Reverse solicitation is also deliberately narrow: it is intended for services initiated at the client’s own exclusive initiative, not as an alternative marketing route. Just as importantly, MiCA authorisation belongs to the specific legal entity and specifies the individual crypto-asset services that entity is permitted to provide.
MiCA also does not remove every payments-law question where e-money tokens are involved. In its June 2025 No Action Letter, the European Banking Authority said that transfers of EMTs carried out on behalf of clients can fall within the payment-services perimeter under PSD2 and recommended a targeted supervisory approach to the resulting dual-regulation issue. In practice, that overlap matters particularly for providers that custody or transfer EMTs on behalf of clients. It is sector context rather than a description of Cryptopocket’s own service scope.
Cryptopocket’s perimeter is intentionally specific. Fintech Payments PSC, S.L., the legal entity operating the Cryptopocket brand, appears in the CNMV register as authorised for the MiCA service of exchange of crypto-assets for funds. Cryptopocket operates a non-custodial model, and its authorisation does not include the separate MiCA services of custody and administration of crypto-assets on behalf of clients or providing transfer services for crypto-assets on behalf of clients. A platform integrating Cryptopocket should therefore read the relationship around that regulated exchange function, rather than assuming that the integration also provides wallet custody or a general crypto-transfer service.
Sources: MiCA Article 3 definitions; MiCA Article 59 authorisation; MiCA Article 143 transitional measures; ESMA guidance on non-compliant ARTs and EMTs; ESMA statement on the end of transitional periods; EBA No Action Letter on PSD2/MiCA; CNMV register of crypto-asset service providers
Block 4. Fiat in, stablecoin out: how a regulated corridor works
At its simplest, a regulated EUR-to-USDC corridor starts with a quote and an identified client. Before execution, the provider needs the onboarding and compliance information appropriate to the client and transaction: identity or corporate information, beneficial ownership where relevant, sanctions and risk screening, source-of-funds evidence where required, destination-wallet information and Travel Rule data where applicable. Fiat funding then arrives through the relevant regulated banking or payment rail. Once the funds are available and the required controls are cleared, Cryptopocket executes the exchange within its authorised service perimeter and settles the purchased crypto-asset to the verified destination specified for the transaction. The fiat leg, the exchange and the on-chain settlement are then linked through settlement evidence and reconciliation records.
The distinction between those steps matters. The banking or payment partner is responsible for the fiat rail it provides. Cryptopocket is responsible for the authorised exchange service and for the compliance controls that apply to that service. The client or integrating platform must provide the information and operational inputs required for the transaction. A regulated corridor works best when those responsibilities are explicit rather than hidden behind a single user interface.
Instant euro payments have changed the experience of the fiat leg. For many euro-area bank accounts, receiving instant euro transfers became mandatory in January 2025 and sending them in October 2025, although later implementation dates apply to certain payment institutions and electronic money institutions. That can reduce idle time between funding and execution. It does not mean every fiat-to-stablecoin transaction is automatically instant: availability still depends on the payment provider, corridor, transaction limits, operational conditions, and completion of the relevant compliance checks.
The compliance layer is often least visible when it is working properly. Screening, transaction monitoring, source-of-funds checks and Travel Rule data can sit behind a smooth flow. When a transaction is held for review, the useful standard is not to promise a fixed completion time, but to explain what information is required, why the review has been triggered, and what happens next. Predictability and explainability are part of the user experience, not simply compliance overhead.
For platforms and fintechs, the integration questions are correspondingly practical: how long a quote remains valid; which assets, networks and jurisdictions are supported; where KYC and KYB responsibilities sit; what statuses and webhooks are available; how fees and limits are applied; what evidence is returned after settlement; how exceptions are handled; and how the fiat and on-chain legs reconcile into the partner’s own ledger. The API matters, but the operating model around the API matters just as much.
Consider a European importer that needs to fund a supplier invoice in USDC. The company is onboarded and, where required, provides the invoice, source-of-funds information, and the supplier’s destination-wallet details. It accepts a EUR-to-USDC quote and funds the transaction through the relevant euro payment rail. Once the required controls are complete, Cryptopocket executes the exchange and the USDC is settled to the verified destination for the transaction. The importer can then reconcile the fiat amount, exchange terms, fees, timestamps and on-chain settlement evidence against the original invoice. The value of the corridor is reduced operational friction and clearer auditability; it should not be presented as a guarantee of universal savings or instant execution.
Vicente Romero, Co-Founder & COO, Cryptopocket: “For a European platform, the key change is not simply that a stablecoin can move quickly. It is knowing which authorised entity performs the fiat-to-crypto exchange, which controls apply before execution, and how the fiat and on-chain legs are reconciled. In a non-custodial model, an authorised fiat-to-crypto exchange service and clear operational accountability make the corridor easier for businesses to integrate, monitor and audit.”
Sources: ECB, Instant Payments Regulation; MiCA Article 77, exchange of crypto-assets for funds
Block 5. The non-dollar question
The European non-dollar stablecoin market is still small relative to the dollar segment, but it is becoming more institutionally structured. One measure of the segment comes from a16z’s April 2026 analysis: non-dollar stablecoin activity spiked above $40 billion when several exchanges delisted USDT for EU users at the end of 2024, then settled at a baseline of roughly $15 to 25 billion a month, higher than before the rules applied. Circle’s EURC is already in circulation under its European issuance framework. Qivalis, the Amsterdam-based company backed by 37 European banks across 15 countries, received authorisation from De Nederlandsche Bank as an Electronic Money Institution in October 2026. As an authorised EMI, it is eligible to issue euro-denominated electronic money tokens. Qivalis says issuance of its planned EMT is expected to begin within the next months and will be subject to the applicable MiCA requirements and publication of the White Paper.
The European Central Bank’s position is more nuanced than a simple endorsement or rejection of euro stablecoins. In a speech on 8 May 2026, ECB President Christine Lagarde acknowledged that euro-denominated stablecoins could generate additional global demand for euro-area safe assets, but argued that the trade-offs, including financial-stability and monetary-transmission risks, mean stablecoins are not an efficient way to strengthen the euro’s international role. In the same speech, she described the underlying distributed-ledger technology as transforming settlement infrastructure. The policy distinction is therefore between the monetary instrument and the infrastructure capabilities that the technology can enable.
Thin liquidity in a non-dollar token tends to have a familiar consequence at the infrastructure layer. Some conversions pass through a dollar leg, which adds a step and a spread. This is a general observation about how liquidity behaves when depth is uneven, rather than a description of any particular pair or any particular service. If a non-dollar segment gains sufficient depth, that intermediate step may become unnecessary for additional pairs, and pricing may adjust accordingly. Whether that happens depends on market data over the next several quarters, not something to assume in advance.
Sources: Circle EURC; a16z, 9 charts on what stablecoins are becoming (24 April 2026); Qivalis, May 2026 consortium update; Qivalis EMI authorisation, 14 October 2026; ECB speech, 8 May 2026
Block 6. Trends worth watching
Market and infrastructure
On-ramps and off-ramps. In its Big Ideas for 2026, published in December 2025, a16z crypto placed better on-ramps and off-ramps at the top of its stablecoin priorities, describing the connection between digital dollars and the financial rails people use day-to-day as the part that remains unsolved. It is a useful observation because it points away from the chains, which have had most of the attention.
Velocity as the more useful metric. If the trend in a16z’s April 2026 analysis continues, the question becomes less how much supply exists and more how often it moves and along which corridors. That is a different measurement problem, and the industry does not yet report it consistently.
Reliability at the edges. Consumer-to-business flows depend on conversion working predictably at both ends of a transaction. In practice, that puts weight on the least reliable link in a chain rather than on the chain’s average quality, which is a reasonable explanation for why integrators have been paying more attention to failure handling than to headline pricing.
Counterparty selection. In markets with written rules, regulatory standing appears to be joining depth and reliability as a criterion for assessing infrastructure counterparties. Stated here as an industry observation, it is not a description of any company’s internal process.
Regulation and market structure
Authorisation and passporting are becoming part of the competitive infrastructure itself. With the maximum MiCA transitional period now over, firms serving EU clients increasingly need to be assessed against the legal entity and services shown in the official registers rather than against legacy national registration or brand-level claims. Passporting can make an authorised service available across the EU without a separate licence in every host Member State, but it does not make providers operationally identical: corridor pricing still depends on liquidity, banking access, supported assets, risk controls and the operating model behind the service.
The MiCA-payment-services boundary for e-money tokens remains one of the areas to watch. The EBA’s 2025 No Action Letter was a practical response to the fact that certain EMT transfers on behalf of clients can fall within both MiCA and PSD2. Its transition period ended on 2 March 2026, following an EBA Opinion published on 12 February 2026 that set out supervisory priorities for national authorities from that date. The issue is most relevant to providers performing custody or transfer activities involving EMTs and should not be read as part of Cryptopocket’s exchange-only MiCA service scope.
Europe and the United States are also building different legal routes around payment stablecoins. MiCA treats single-currency stablecoins as e-money tokens and links issuance to the EU e-money framework. The US GENIUS Act, signed into law on 18 July 2025, created a federal framework for permitted payment stablecoin issuers, including reserve and disclosure requirements and provisions addressing certain foreign issuers. For platforms serving both markets, the practical task is not to assume automatic equivalence: issuer eligibility, token availability and the authorisations of the service provider need to be mapped separately in each jurisdiction.
Sources: a16z Big Ideas for 2026; EBA No Action Letter on PSD2/MiCA; EBA Opinion, 12 February 2026; US GENIUS Act, White House signing notice
Block 7. What this means for someone moving between fiat and stablecoins
A few things are worth checking before moving value between fiat and stablecoins, regardless of which service is involved.
Check the authorisation status of the entity you actually contract with rather than the brand above it. Regulators publish registers, and the register entry is more informative than a website claim.
Expect the availability of specific tokens to differ between markets. That can reflect regulatory or commercial factors rather than a technical fault, and a service that explains which applies is more useful than one that simply shows an error.
Treat the fiat leg and the stablecoin leg as separate variables. Fiat settlement can be near-instant in some corridors, while the speed of the stablecoin leg depends on the network involved.
A compliance hold may form part of a regulated flow. What distinguishes a good provider is how it handles that hold: it explains what information it needs and what happens next.
Where users control their own wallets, they should confirm the destination address and network before a transaction is sent, and confirmed blockchain transactions may be irreversible. Providers should supply clear network information, checks and warnings to reduce avoidable errors. How responsibility is allocated in a specific case follows from the applicable customer terms and legal framework.
Closing
Stablecoins are becoming part of financial infrastructure while several jurisdictions have put core regulatory frameworks in place. Implementation and market practice are still developing. The next stage is less about whether value can move on-chain and more about whether the full corridor can work predictably, from fiat funding and compliance checks through the exchange itself to network settlement and reconciliation. This piece places the regulatory and engineering perspectives side by side and describes where they meet.
Author note
This article was prepared jointly by SimpleSwap and Cryptopocket. SimpleSwap contributed market and infrastructure observations; Cryptopocket contributed EU regulatory and regulated fiat-to-stablecoin operating context.
Cryptopocket is the brand of Fintech Payments PSC, S.L., authorised by the Spanish CNMV under MiCA for the exchange of crypto-assets for funds; its official domain is cryptopocket.io.
SimpleSwap is a self-custodial multi-source swap aggregator operating since 2018; its only official domain is simpleswap.io.
Each company is responsible for the factual accuracy of its own contributions, while shared sections were reviewed jointly. The article is provided for general informational purposes only and does not constitute legal, financial, investment or regulatory advice. Crypto-assets involve risk, including the possible loss of funds; each company’s risk disclosures are set out in its terms of service. Regulatory status and service permissions should be checked against the relevant official registers at the time of reliance.
Web: Cryptopocket | SimpleSwap