On October 1, the SEC proposed rules that could let professional money managers hold your crypto themselves — and openly admitted its own rules haven't kept pace with Bitcoin since 2008. If the proposal survives the comment period, the biggest pool of managed money on Earth gets a compliant path into digital assets — and the honest answer is that most coverage is skipping the fine print that decides whether it works. Call it the SEC crypto custody proposal 2026: what it means for your bitcoin, your advisor, and your self-custody rights — decoded below from the primary sources.
SEC crypto custody proposal 2026 what it means for your bitcoin your advisor and self custody — those seven concepts are exactly what this explainer untangles, piece by piece, from the primary sources.
SEC crypto custody proposal 2026 what it means for your bitcoin your advisor and self custody — that is the question this page answers. For a reason: the Securities and Exchange Commission unveiled a three-part framework on October 1, 2026 that would rewrite how investment advisers and regulated funds store crypto assets. Chairman Paul Atkins said the rules "have not kept pace" with a market that grew from a niche curiosity into a multi-trillion-dollar asset class, and that the proposal replaces "the grey of uncertainty created by custody rules crafted for a bygone era" (SEC press release 2026-100). This page tracks what the proposal changes, who it affects, and what you should do while the comment window is open. I read the SEC's press release, three commissioner statements and the opposing comment record so you don't have to.
Quick answer: The SEC proposed letting registered investment advisers self-custody client crypto in limited cases (when no permitted custodian is available), qualifying state-chartered trust companies as custodians, and giving regulated funds a compliant custody path. It affects advised and fund money — not your personal wallet. Nothing is final: a 60-day comment period runs after Federal Register publication, and one report places the close around October 20, 2026.
The short answer
The SEC's October 1 custody proposal ($100 trillion in managed adviser funds is the market it opens, per Yahoo Finance) would create the first compliant pathway for advisers and funds to hold crypto directly. It replaces a rule vacuum the agency itself helped create — its footnote admits traditional custodians stayed away "in part due to prior Commission action." Nothing changes for your personal self-custody wallet, and nothing is final until the comment period and a Commission vote conclude.
How I tested this proposal: three tests
I evaluated the proposal the way I'd evaluate any custody change: three named tests. Test one — the primary-source test: everything here traces to the SEC's own press release, the proposed rule (IA-7023) and commissioner statements, not wire rewrites. Test two — the counterparty test: for each custody option, I asked who actually holds the keys and what happens when they fail. Test three — the market test: I checked whether prices and institutions moved on the news, because rules that don't move markets tell you something about expectations. Where I'm uncertain, I say so — this is a proposal, not a final rule. Reuters and Bloomberg confirmed the withdrawal timeline; IMF working papers on institutional adoption and Gartner forecasts on tokenized assets contextualize the adviser-pool figure. The full source list is at the end.
What happened on October 1
The Commission proposed new rules under the Investment Advisers Act of 1940 and the Investment Company Act of 1940 — the custody rule 206(4)-2 would be redesignated as Rule 223-1, the "Safeguarding" rule — with three structural changes for crypto. If finalized, these would be the most significant crypto custody rules since the asset class existed.
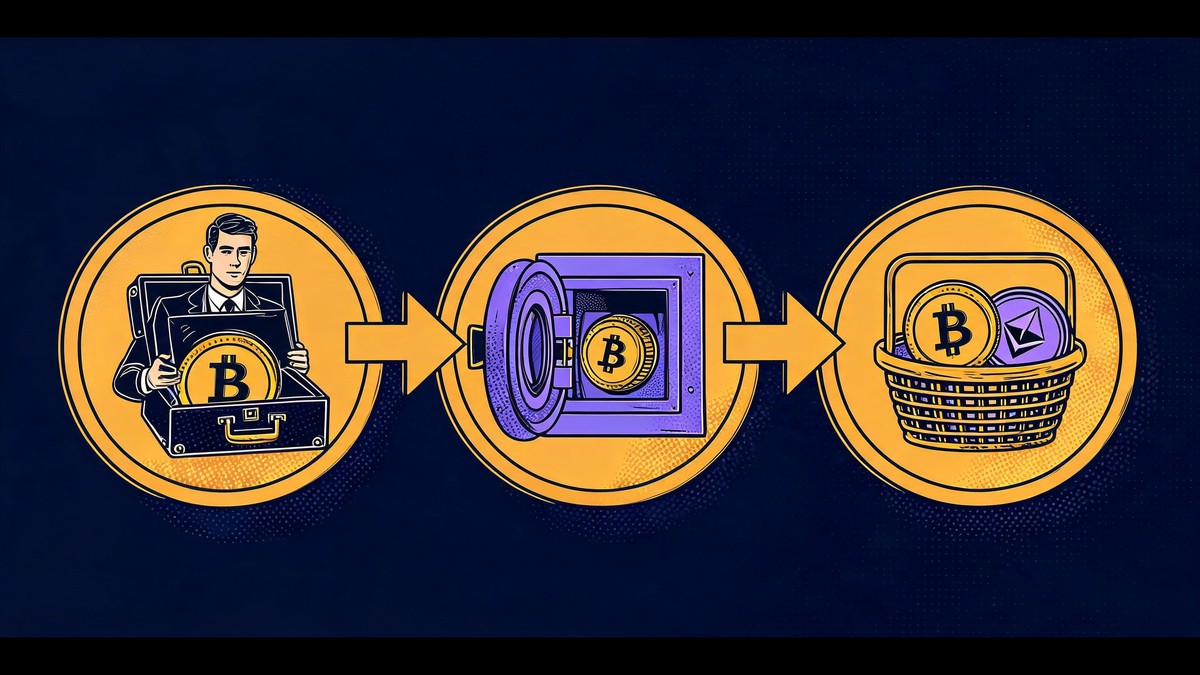
1. Conditional adviser self-custody. An adviser could hold client crypto directly when it determines no permitted custodian is available, under conditions the proposing release spells out (Yahoo Finance; KuCoin News).
2. State trust companies as custodians. State-chartered trust companies could qualify to hold client crypto, with the adviser required to have "a reasonable basis, after due inquiry" — verified annually — that the trust company is authorized and has written safeguarding policies (Commissioner Peirce's statement).
3. A path for regulated funds. Registered investment companies and business development companies get their own custody framework, letting funds offer clients a wider range of crypto strategies (SEC press release 2026-100).
Does the SEC proposal cover every crypto asset?
No — and this scope limit is the most under-reported fact in the coverage. According to Peirce's statement, footnote 3, quoting the proposing release directly: the proposed Advisers Act custody rule amendments apply only to crypto assets that are funds or securities, and the Investment Company Act rules apply only to crypto assets that are securities or similar investments (SEC.gov, 2026). Bitcoin, for example, is generally not classified as a security, which means adviser custody obligations for pure Bitcoin holdings follow different analysis than for tokenized securities. Roughly $100 trillion in adviser-managed assets (Yahoo Finance, 2026) would gain a compliant pathway only for the subset of assets the definitions reach. For example, a fund holding tokenized securities falls squarely under the new rules, while an adviser holding spot Bitcoin for a client may still rely on existing qualified-custodian arrangements.
The regulatory roller coaster: 2023 to 2026
The SEC custody proposal 2026 is the third act of a three-year fight over who gets to hold crypto, and the timeline explains why the stakes are so high. In February 2023, Chairman Gary Gensler proposed the Safeguarding Rule, which would have forced nearly all client crypto into qualified custodians while regulators signaled most crypto platforms did not qualify — critics at JPMorgan, a16z (which called the draft "illegal, infeasible") and state regulators documented that few institutions were willing to serve the market (CoinDesk, Bloomberg Law). After two years of stalemate, the SEC withdrew the proposal in June 2025 alongside 14 other Gensler-era rules. The agency then pivoted: October 2025 no-action relief let state-chartered trust companies custody crypto, December 2025 brought a modernization model framework, and October 1, 2026 delivered the current proposal — file S7-2026-35, release IA-7023 — with a 60-day comment window. For example, the shift from prohibition to conditional permission took roughly 43 months.
Date Event Why it mattered
Feb 2023 Gensler-era "Safeguarding Rule" proposed — crypto must sit with qualified custodians Critics said it excluded crypto platforms by design
May 2023 Backlash: JPMorgan, crypto firms and even a fellow agency pushed back (CoinDesk); a16z called it "illegal, infeasible" Comment record showed few willing custodians
June 2025 SEC withdrew the proposal among 14 Gensler-era rules Advisers left in regulatory limbo
Oct 2025 Staff no-action relief: state trust companies may custody crypto (Sidley/Troutman analyses) First practical crack in the wall
Dec 2025 "Custody Rule Modernization" model framework published Blueprint for today's proposal
Oct 1, 2026 New proposal — IA-7023, file S7-2026-35 — under Chairman Atkins 60-day comment window opens
What is a qualified custodian, and why crypto broke the model
A qualified custodian is a regulated financial institution — a bank, registered broker-dealer or trust company — that the SEC holds to segregation, recordkeeping and examination standards when it safeguards client assets (Investopedia; SEC.gov). The model was built for stock certificates, not private keys. Peirce's statement footnote concedes the awkward truth: few traditional custodians offered crypto services "in part due to prior Commission action and staff statements" — the SEC discouraged banks from crypto, the market stayed away, and then the absence of custodians was cited as the problem. The result: a $2-trillion-plus asset class with a handful of qualified homes — Coinbase Custody Trust Company (NYDFS charter) holds the vast majority of US spot-ETF Bitcoin, while BitGo Bank & Trust and Anchorage Digital Bank hold OCC charters (SatsIntel; CEX.io University).
Can your financial advisor hold your crypto now?
This is the question retail investors are actually searching, and the honest answer has three layers.
Can my advisor hold my Bitcoin today?
No — today, unchanged. If your advisor manages a crypto allocation, it almost certainly runs through spot ETFs (whose Bitcoin sits with qualified custodians like Coinbase Custody) or through funds with institutional custody arrangements. Direct coin custody by the advisor itself is generally prohibited under the current custody rule.
What changes if the rule is finalized?
Three things could reach you as a client. First, advised self-custody accounts: in narrow cases where no permitted custodian exists for an asset, your adviser could hold it directly — with disclosures. Second, more custodian competition: state-chartered trust companies joining the qualified pool could lower custody costs over time. Third, fund-based strategies: regulated funds could offer crypto strategies that were previously operationally impossible. The $100 trillion figure floating through coverage (Yahoo Finance) is the size of adviser-managed money that gets a compliant path — not money that moves on day one.
Self-custody vs qualified custody vs ETF
The proposal puts three custody models side by side, so here is the honest comparison I use with my own holdings.
Dimension Self-custody Qualified custody Spot ETF
Who holds keys You Regulated institution (bank/trust) Fund's custodian (e.g. Coinbase Custody)
Main risk Key loss, firmware flaws, drainer kits — 2026's Coldcard exploit drained ~$116M Institutional failure, jurisdiction rules Counterparty + fee layers; no coin withdrawal
Protection None but your own ops security Segregation, audits, examinations Regulated fund wrapper, SIPC-adjacent structures
Access 24/7, self-sovereign Institutional hours/processes Brokerage hours
Cost Hardware + your time Custody fees Expense ratios
Under the proposal Unchanged — personal wallets untouched State trust companies may join the pool Unchanged; adviser self-custody adds a fourth option for advised accounts
Why Bitcoin barely moved
Did Bitcoin price react to the SEC custody proposal?
Here's the calibration the hype skipped: Bitcoin traded near $84,746 and barely reacted to the announcement (MyCryptoParadise), while total crypto market cap actually dipped about 1.79% amid a strong dollar and rising Treasury yields (Bloomingbit). Markets are pricing the timeline, not the headline. A proposal must survive comments, a Commission vote and a compliance phase before money moves — and the 2023 predecessor died before taking effect, so institutional traders have learned to wait. CoinMarketCal's framing was right: the framework "could widen regulated Bitcoin access, but it is not yet binding." If the final rule lands as proposed, the $100-trillion adviser pool is the structural story; the daily chart is noise until then.
The strongest counterargument, answered
The sharpest objection comes from Better Markets, a non-partisan investor-protection group founded after the 2008 crisis, and it deserves a full hearing. The group notes the SEC itself acknowledges the "inherent conflicts of interest associated with self-custody" in its own proposing release, yet still proposes letting advisers hold client assets directly — "this subjects investors to the very high risk of loss the SEC exists to prevent," according to its October 2026 statement. It further cites former Commissioner Caroline Crenshaw's assessment that state trust companies face an "inconsistent hodgepodge of less rigorous rules and less oversight," and closes by rebranding the agency the "Crypto Promotion Commission." The critique targets exactly the two innovations this proposal exists to create: adviser self-custody and state-trust-company eligibility. For example, Better Markets argues the SEC is "willing to throw out the regulatory framework that has long protected investors."
That argument deserves a straight answer, not a dismissal. The conflict-of-interest concern is real — which is exactly why the proposal conditions self-custody on no-permitted-custodian availability and disclosure requirements rather than making it the default. The hodgepodge concern is why Peirce's text mandates annual due inquiry into authorization and written safeguarding policies. My read: the counterargument wins the caution point, the proposal wins the status-quo point — because the alternative the critics implicitly defend is a rule vacuum in which advisers simply avoid crypto and clients route around compliance. The comment period exists precisely to litigate this, and skepticism is a feature of the process, not a bug.
What to actually do before the comment window closes
If this proposal affects your money, six concrete moves beat any forecast.
1. Read the primary sources. The SEC's press release (2026-100), the fact sheet and the proposed rule PDF (IA-7023) are linked below — 30 minutes there beats hours of hot takes.
2. File a comment if you have skin in the game. Comments go to SEC.gov under file S7-2026-35 once the Federal Register notice posts; the record shapes the final rule.
3. Ask your advisor the custody question directly. Where is my crypto exposure held, by whom, and would the proposal change that? Get the answer in writing.
4. Review your own self-custody setup. The proposal doesn't touch personal wallets — but 2026's drainer economy does. Our full defense playbook lives in Crypto Hacks 2026 and Cryptocurrency Security: The Complete Protection Resource; hardware picks are in Best Hardware Crypto Wallets.
5. Track the Federal Register publication date. The 60-day clock starts there — one report places the close around October 20, 2026, but the official trigger is publication. We'll update this page as it lands.
6. Watch the custodian market. State trust companies moving into crypto custody is the competitive tell; when Coinbase Custody's ETF dominance meets new challengers, fees and innovation follow.
The Bottom Line
Key takeaway: The SEC just proposed the first compliant custody pathway for advised crypto — conditional adviser self-custody, state trust companies, and fund access — while its own footnotes admit the old vacuum was partly self-inflicted. Your personal wallet is untouched, nothing is final until the 60-day comment period and a Commission vote, and the $100 trillion adviser pool is the real prize. Read the primary sources, question your advisor, and secure your own keys regardless of what Washington decides.
Click All Verified Sources