
PUNZI Papers Essay Ten · The Debt-Ponzi We All Find Ourselves Trapped In
This essay is part of The PUNZI Papers, a series of essays explaining the reason for our project, PUNZI WARS, and the potential we think it points to.
Visit us: https://punzi.xyz Follow us: Lens (Hey) · NOSTR (Primal)
Advisory: PUNZI WARS is a game and an on-chain research experiment. It is not an investment. Participate at your own risk.
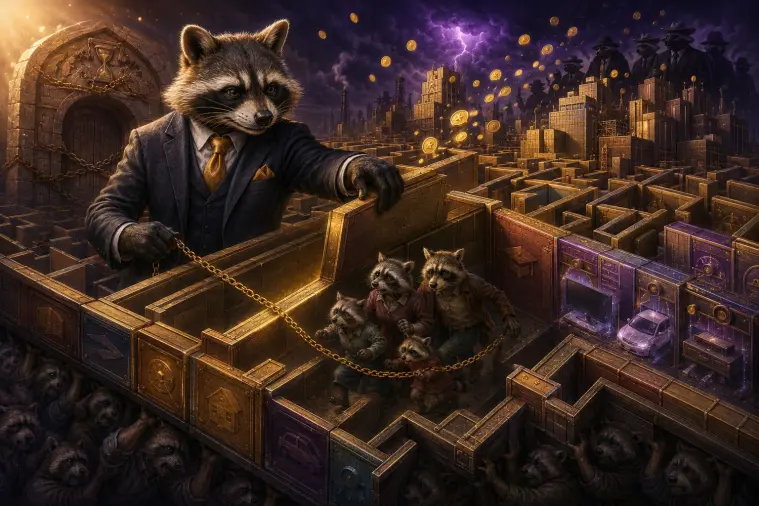
The earlier essays of this series anatomised the Ponzi-like machinations that modern finance and society run on, institution by institution. This essay looks at the individual standing within that machinery. An ordinary life, examined closely, turns out to be a small bundle of promises to pay (a mortgage, a tuition loan, a car note, a premium, a tax) owed to people one will never meet, against a future that can be revised upward. Those claims can change over a lifetime; their weight is hardest to carry when wages and savings leave little room. In short, many of us find ourselves navigating a Ponzi-like labyrinth of debt and recurring costs.
A Life, Itemised
The essays so far have examined the load-bearing institutions of modern finance one at a time, and found the same Ponzi-like structure inside each. This essay is about the people that all of them finally rest on, and specifically about the floor. It is worth coming down out of the architecture for a moment and being where most of the population actually stands, which is at the bottom of it, holding the bill.
Consider an ordinary life, not as a story but as an accountant would see it: a set of obligations to pay, arriving in sequence. There is life-long debt taken on to become employable in the first place, because the qualification that the wage now requires costs more than the wage could provide outright. There is the debt taken on to be housed, because the price of a house long ago detached from any wage that could buy one outright. There is the debt taken on to reach the work, because the work is somewhere the public transport is not. There is the short, expensive, revolving debt such as credit cards and short-term loans that bridges the recurring gap between what the month costs to live and what the wage covers. There is the premium paid every month against the possibility of illness, and the tax deducted before the wage is ever seen. Each of these was sold as a form of access, and each is, in plain mechanical terms, a claim on labour the person has not yet performed.
The aggregate is now a matter of public record. At the close of the third quarter of 2025, American households owed $18.59 trillion, then a record. Mortgages accounted for $13.07 trillion; auto loans for $1.66 trillion; student loans for $1.65 trillion; and credit-card balances for $1.23 trillion. Nearly 5 per cent of outstanding debt balances (roughly one for every 20) was in some stage of delinquency that quarter.
The shape worth noticing is not the size of any one number but the obligations they describe together. The instruments differ, as do their purposes and terms. A loan can make a skill, a home, or transport available now in exchange for payments from future income. Interest adds to the cost; on an amortizing loan, the interest portion of a payment is generally larger at the start, when the unpaid balance is larger, while revolving credit follows a different pattern. Borrowing can solve an immediate need and still leave a household with less room in its future budget. The borrower runs, and at times the running keeps them in roughly the same place, which is the sensation behind the treadmill image. The better image here is a labyrinth because in a labyrinth the walls move.
Money Is Somebody’s Debt
There is a fact about much of the money itself that a household budget rarely has to confront. Banks create deposits when they lend.
The banking essay, earlier in this series, set this out and it bears restating. When a commercial bank makes a loan, it does not simply transfer a pre-existing deposit from one customer's account to another. It records a loan as an asset and creates a deposit as a liability; that deposit is new money. Commercial bank lending creates much of the money used in the economy, and each new bank loan creates both a deposit and an obligation to repay. But not every dollar of money comes from a bank loan, and not every debt creates new money. Money and debt are deeply connected, without being the same stock or having to grow in lockstep.
The totals nevertheless show how much debt the global economy carries. The Institute of International Finance put the world's total debt at $348 trillion at the end of 2025, a little over three times annual global output, having added some $29 trillion that year. That aggregate joins obligations with different borrowers, lenders and repayment terms. Some are paid off, others are refinanced, and new borrowing is added. A household seeking to clear its own debts is therefore doing something distinct from reducing every balance across the global economy. The scale of those balances still matters, because debt service is a claim on future income.
The Walls That Move
It would be one thing to take on debt in a world where the obligation could steadily be worked off against a wage rising as quickly as the value produced at work. That is not how gains have been shared over the last several decades.
From 1979 to 2025, net productivity in the United States rose by about ninety per cent. Inflation-adjusted hourly compensation for typical workers, including benefits, rose by about thirty-three per cent. For the thirty years before 1979, the two measures had climbed at similar rates; after that they came apart. The widening gap is real, but it does not mean typical workers took home less in real terms: the cited series shows compensation rising, though far more slowly than productivity. Net output per hour across the economy is nearly twice its late-1970s level, while typical workers’ real compensation rose by only about a third.
That gap can make necessary expenses harder to meet, especially where their prices rise faster than a household's income. Housing requires a large mortgage for many buyers. Higher education and serious medical care can bring bills that ordinary wages cannot readily cover from savings. Credit can bridge those gaps, but it also commits future earnings. The pattern is that inflation-adjusted compensation rose far more slowly than productivity, while some necessary expenses rose faster than many households could comfortably meet from income. Borrowing often fills part of that gap.
This is the sense in which the walls move. A treadmill at least holds still under the feet. A household can reach a position it was told to aim for (take on the degree to get the job, or seek a mortgage to buy a home) only to find that pay has not kept pace with the price of that goal. The target can recede while the household approaches it, and taking on debt may be the available route to close the distance. That does not make every household's experience identical, but it does make the price of access a claim on future wages.
The Recurring Bills
Three large recurring claims on an ordinary life are not debts in the strict legal sense, but they belong in this account because they consume income before it can be used elsewhere. Their amounts can rise or fall, and households have varying degrees of choice about them; in practice, many cannot simply decline the underlying need.
The first is the cost of health care. The United States spent $5.3 trillion on health care in 2024, eighteen per cent of everything the economy produced that year, or $15,474 per person on average. A great deal of the household's share arrives as an insurance premium, paid whether or not care is needed. Insurance can still leave substantial deductibles, copayments and coinsurance, and care outside the network or outside the policy can bring further bills. Costs a household cannot meet can become medical debt. Estimates put outstanding U.S. medical debt at at least $220 billion; survey definitions that include payment plans and borrowing to meet bills find that many adults carry some form of health-care debt. Coverage does not remove financial risk of illness.
The second is taxes. Federal interest costs compete with other uses of public revenue, and borrowing today can constrain the budget choices of future taxpayers. But the payroll contributions for Social Security and Medicare have a different purpose: they finance those programmes, not federal debt service. In 1937 the Social Security rate was 1 per cent for employees and 1 per cent for employers. In 2026 the employee's Social Security and Medicare rates total 7.65 per cent; the employer pays another 7.65 per cent, while the general self-employment rate is 15.3 per cent. Those rates have changed over time, but their history does not establish that every tax must rise as federal debt rises. The household still has to meet a recurring tax bill alongside its other obligations.
The third is newer than either: recurring payments for things households once tended to buy outright. Music and films are often licensed by the month, and access can end when payment stops. Software is now sold as a continuing service rather than a disc kept on a shelf or a programme someone owns. Cars and major appliances are following suit, requiring consumers to pay for ‘premium features’ already built within the items sold by locking the item’s capabilities behind software. And nearly every good and service seems to be extending this same model. Quality suffers while actual costs and expenditures go up.
Each charge may be small; together they add another recurring claim on the household budget, for access a household may be reluctant to give up. It is the same structure the earlier Punzi Papers market essays found in a company valued on recurring revenue, seen from the paying end: what the corporation books as a dependable future inflow, the household books as a continuing expense. Renting can be useful, and ownership can carry costs of its own. But the more a household substitutes ongoing access for durable property, the less it may have to sell, lend, or leave behind when the payments end.
The Asset and Its Price
Set against this ledger of claims is the asset many households hope will balance them: a home. For an owner-occupier, it can be the largest item on the household balance sheet and a visible form of accumulated wealth. Other households rent, and homeowners may hold savings, retirement accounts or other assets too. A home provides shelter and is physically there, yet the number assigned to it on a balance sheet is a market price shaped by conditions far beyond its walls. It is one of the most easily misunderstood numbers in the account.
A home is presented to the household as wealth, and the wealth is read off its market price. But the building does not become newer as it ages: the roof wears, the wiring dates, and the structure needs upkeep. The structure itself wears out and costs money to maintain. Yet an owner-occupied home also supplies shelter, while its site includes land whose value can change independently of the building. A higher sale price can reflect land, location, demand, supply, financing conditions and inflation. Some of a nominal gain may be lost to inflation or to the cost of buying another home; the whole increase cannot be reduced to a shrinking measuring unit.
Two consequences follow, and both complicate the owner's sense of being richer. The first is that a gain on a family's only home is not cash ready to spend without another choice. Selling means finding somewhere else to live, perhaps in the same expensive market, and paying transaction costs. A household with one home can sometimes realise part of a gain by moving to a cheaper home or place, or access equity through a loan, though each route brings costs, risks or a change in housing. An owner of additional property can sell an asset without surrendering their own home. Rising home prices therefore create very different opportunities for owners with one home, owners with several, and people still trying to buy.
The second consequence is that the same price rise that flatters the owner can be a barrier to whoever does not yet own. When prices outrun wages, a new buyer may need a larger mortgage, a longer term or a greater share of earnings to buy a comparable home. Some can choose a smaller home, a cheaper place or no purchase at all, but each choice has a cost. The incumbent's potential gain and the newcomer's burden are linked by the price they negotiate; the rising number is not an unqualified gain for the household sector as a whole.
The Incentive and the Cost
It is tempting to read this strain as a problem confined to people who made poor choices or suffered bad luck. Those explanations miss the incentives that sit alongside individual decisions. Credit can help a household buy a home, gain a qualification or weather an emergency, while interest payments give a lender income as long as a performing loan remains outstanding. The benefit of access and the continuing cost can both be real.
From a lender’s side, a performing loan brings interest income; repayment ends that stream. That can reward continued lending, but lenders also face defaults, funding costs, competition and rules, and debt-free customers can still use their services. Insurance premiums and taxes are different kinds of obligations, paid to institutions with different purposes. From a household’s side, their combined weight with loan payments can commit future wages and narrow the room to absorb a setback or reject poor terms. No single lender designed that whole burden, but the incentives and obligations deserve examination together.
The distribution of wealth helps show why the pressure falls unevenly. The Federal Reserve's accounts record that the bottom half of American households, ranked by wealth, holds about two and a half per cent of the country's wealth between them. That aggregate does not show how any one household would withstand illness or lost work. Households in this group own assets, including homes and retirement savings, and carry debts; their holdings are small beside those of wealthier households. When debt service and recurring charges consume wages, those with less wealth have less room to absorb a setback. This can transfer income from borrowers to lenders and other claimants, though the terms and benefits of each obligation differ. It is people with the least cushion who are most exposed to the strain.
The older name for a much harsher form of debt constraint is debt bondage. Across history, some people unable to repay a debt were forced to work under coercive conditions called debt bondage, a form of unfreedom (i.e. slavery). Ordinary borrowing can severely constrain a person's choices, but it is legally distinct from debt bondage and forced labour. Ancient texts and reforms addressed debt and its social consequences. The Hebrew Scriptures describe a fiftieth-year Jubilee of release and return to family property, alongside a separate seventh-year remission of certain debts; Solon, in Athens in 594 BC, cancelled debts that had pledged the poor and their persons to the rich, and forbade lending secured on the body; the book of Proverbs warned that the borrower is a 'slave to the lender'.
There is no automatic fiftieth-year cancellation of today's household debt. Some debts are refinanced or rolled forward, and an unpaid balance can diminish the estate left to a family. A worker whose future earnings are pledged to a mortgage or other loan has less room to use those earnings for something else. The contracts involved are legally different from coercive debt bondage, but their payments can still constrain household choices for years. Many people will reach the end of working life having serviced obligations for decades and owning less than when they started.
The Thread Through Every Door
The institutions this series has examined are so many doors into a single building, every one of them opening onto the same machine. It is worth saying what the floor of that building is made of, because the floor is the subject of this essay, and the answer is the same in every room.
Behind many of these doors is a claim on future income, and households are the ones who pay it. Public debt interest is met from government revenue or further borrowing. Commercial-bank lending can create deposits, while a mortgage commits the borrower to future payments. Higher asset prices require a larger mortgage from a new buyer. Social Security is financed largely by current workers' payroll contributions, which support current beneficiaries. Stock purchases and retirement saving can also support asset prices, while corporate buybacks change the number of shares outstanding. These mechanisms differ, but each helps show how financial decisions made far from a household shape its budget.
Institutions are linked both to one another and to the people who borrow, pay insurance premiums, save and pay taxes. Their payments support lenders, insurers, governments and markets in different ways. However, the effects do not fall evenly: a recurring claim takes a larger share of the financial room available to a household with little wealth. That is the human cost this essay asks the reader to keep in view.
Three Readings of One Condition
The three questions this series puts to any Ponzi-like structure apply to the debt economy as cleanly as to any single institution within it, and return, as they have throughout, three views of the same thing.
The first is efficiency: how much of the value moving through the structure is taken before it reaches the people it is supposed to serve. Interest is one toll on the household's access to homes, education, cars and short-term credit. Lenders also provide a service and bear risk, so the entire interest payment cannot simply be treated as value removed without comparison to what the loan makes possible. Yet interest remains a substantial, continuing claim on many households' income. It is collected on much of the debt households carry. The size, rate and duration of each obligation determine its cost.
The second is transparency: whether the participant can understand what they are inside. Many key terms are disclosed. The annual percentage rate is printed, the premium is itemised, the tax code is extensive, and terms of use can be long and difficult to read. A document may satisfy a disclosure duty while its length, framing, or technical language makes the risks hard for an ordinary person to assess. Debt is sold as access, the loan as an investment in oneself, the mortgage as ownership, the premium as peace of mind, the whole apparatus as freedom and choice and getting ahead. Such descriptions can be useful, but they can also steer attention away from obligations and costs. The reader may have the terms in hand without a clear picture of how those terms will bear on a household budget. That is the functional opacity this series has tracked through every institution, here applied to the household's own front door.
The third is longevity: whether the structure survives when payments or incomes no longer support its promises. Households may borrow, refinance, or roll over balances, but each path has a cost and depends on future income, credit, or asset values. Debt can grow for long periods; it cannot outrun the income available to service it indefinitely. The New York Fed reported 4.5 per cent of balances in some stage of delinquency in the third quarter of 2025, roughly flat from the previous quarter. That share describes present strain, not a clock that predicts when or whether a wider structure will break.
The Increasing Strain of Modern Life
What all of this produces, taken together and at scale, is strain. A household carrying debt while trying to meet housing, health-care and tax bills has less room to absorb a setback or pursue a new opportunity. Typical real compensation has risen, but much more slowly than productivity, and some essential costs have risen faster than many households' income. Multiply that pressure across a population and it becomes part of society's background stress.
The load is not shared out evenly, though the wealth figures alone do not measure who pays the greatest share of income in debt service and recurring bills. A household with little savings has less room to recover from a setback, and families can pass both assets and disadvantages across generations. The sensation of running hard to remain in place can follow when a goal such as housing or education grows more costly even as wages rise. The people facing that pressure cannot be judged as a group by thrift or imprudence alone; the terms available to them matter too.
A structure under mounting strain cannot continue unchanged forever. Reform and collapse are the familiar exits. It can be reformed deliberately, while there is still room to choose how costs are shared, rather than leaving the distribution to chance when it gives. Or it can break on its own schedule, and let the costs fall where the breaks occur. There is no path in which obligations can outrun the resources that service them without limit. The inflow that keeps a debt-funded arrangement upright is finite, even if its timing and sources can change.
This leaves a question worth ending on. If the maze cannot be run forever, and breaking it can harm the people who have the least room to absorb the loss, might replacement offer another route? Could a system built on debt, opaque terms, and the unequal distribution of claims be transitioned toward different principles? It is a question, not a cure. The next essay considers how far any proposed alternative can go.
Conclusion · The PUNZI Papers Essay Ten
This completes the present essay of The PUNZI Papers, a series of essays explaining the position behind our project, PUNZI WARS, and the potential it points to.
In the next essay: Can Honesty and Transparency Fix Society’s Ponzi Problems?
Visit us: https://punzi.xyz Follow us: Lens (Hey) · NOSTR (Primal)
Advisory: PUNZI WARS is a game and on-chain research experiment. Participation can result in financial loss. Participate at your own risk.
Sources
-
Federal Reserve Bank of New York, Household Debt and Credit Report (Q3 2025; balances by category and 4.5 per cent of outstanding balances delinquent)
-
Institute of International Finance, Global Debt Monitor (2025; world debt approximately $348 trillion, around three times global output)
-
U.S. Department of the Treasury, Fiscal Data: Understanding the National Debt (gross federal debt approximately $39 trillion, 2026)
-
Centers for Medicare & Medicaid Services, National Health Expenditure Data (2024; $5.3 trillion, 18.0 per cent of GDP, $15,474 per person)
-
KFF (Kaiser Family Foundation), The Burden of Medical Debt in the United States (at least $220 billion outstanding; share of adults carrying health-care debt)
-
Federal Reserve Board, Distributional Financial Accounts (share of household wealth held by the bottom 50 per cent)
-
Economic Policy Institute, The Productivity–Pay Gap (net productivity and typical worker compensation, 1979–2025)
-
Social Security Administration, Historical payroll tax rates (employee and employer shares, 1937–2026)
-
David Graeber, Debt: The First 5,000 Years (2011)
-
Michael Hudson, …and forgive them their debts: Lending, Foreclosure and Redemption from Bronze Age Finance to the Jubilee Year (2018)
-
Bank of England, Money creation in the modern economy (2014; bank lending and deposits)
-
HealthCare.gov, Coverage and Out-of-pocket maximum/limit (essential benefits and cost sharing)
-
Social Security Administration, 2026 Social Security and Medicare tax rates; What are the Trust Funds?
-
Bureau of Economic Analysis, Housing Services (owner-occupied shelter services)
-
Federal Housing Finance Agency, Residential Land Prices: Growth Rates, Spatial Gradients, and Elasticities (2019)
-
Consumer Financial Protection Bureau, Using home equity to meet financial needs; Does a person's debt go away when they die?; What is a grace period for a credit card?
-
Leviticus 25:8–13 and Deuteronomy 15:1–2 (Jubilee and seventh-year remission)
-
Internal Revenue Service, A Guide to Common Qualified Plan Requirements (plan assets held in trust)
-
International Labour Organization, Fighting human trafficking: the forced labour dimensions; The meanings of forced labour
-
Consumer Financial Protection Bureau, What is amortization and how could it affect my auto loan?; How does my credit card company calculate the amount of interest I owe?





